REPLYLEAD / INDUSTRY FIELD GUIDE
Fintech lead generationConnect the workflow.
Expose the dependencies.
Distinguish the user, integrating team, and institution that approves the purchase.
THE BUYING PROBLEM
Fintech is a market.
What is the decision?
Fintech lead generation should distinguish selling software to a business, integrating with a platform, and distributing a financial product. This playbook covers B2B software and vendor conversations. Begin with the supported workflow, deployment model, jurisdiction, and buying organization. Separate commercial interest from technical compatibility and from any regulated approval process.
The costly targeting mistake
Funding and hiring announcements are context, not proof of purchasing intent. Do not infer transaction volume, fraud exposure, creditworthiness, or an upcoming provider switch. A payment-related job title does not tell you who owns integrations or procurement.
01 / WORK THE PROBLEM
Fintech integration-dependency mapper.
A product demo cannot resolve who owns the integration. Map the workflow, data scope, system owners and test environment before proposing a pilot.
Illustrative inputs loaded. Edit them to build your own brief.
Calculations run in your browser. This tool makes no live account lookup. Our tool events record action names, not your field values.
YOUR WORKING BRIEF
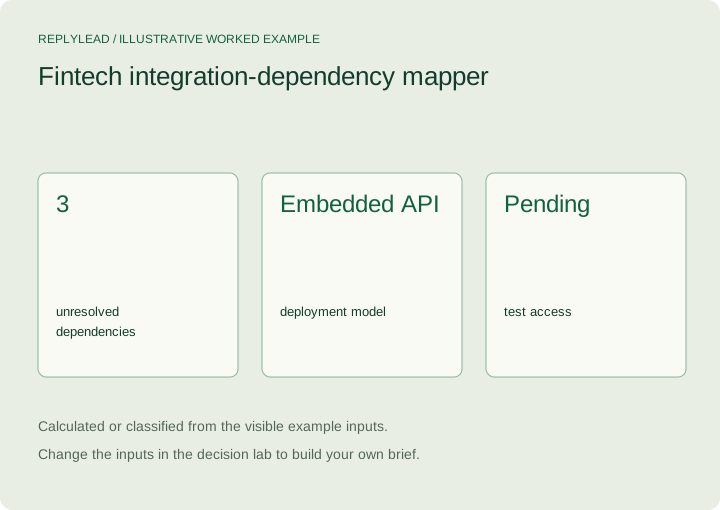
3 integration dependencies to resolve
| Requirement | Decision |
|---|---|
| Workflow | Accounts-payable reconciliation |
| Deployment | Embedded API |
| Source-system owner | Confirmed |
| Data movement | Not mapped |
| Test environment | Pending |
| Implementation owner | Unknown |
Next actions
- Map data fields, direction, retention responsibilities and review requirements.
- Resolve test-environment access before scheduling a technical pilot.
- Name the implementation owner and responsibilities.
- Verify supported interface versions and acceptance criteria with both technical owners.
02 / FOLLOW THE REASONING
Watch the evidence
change the next step.
ILLUSTRATIVE CASE / NOT A CLIENT RESULT
A partnership label hides the work
A hypothetical accounts-payable platform considers an embedded reconciliation API. Commercial interest does not define the implementation boundary.
Draw the dependency chain
The source-system owner is known. Data fields and movement remain unmapped, the test environment is pending, and no implementation owner has accepted the work.
Make the pilot proposal conditional
Prepare a data-flow discussion and name the implementation owner before scheduling a pilot. The output is a technical discovery agenda, not an integration compatibility claim.
03 / SELECT THE COMMERCIAL ROUTE
Different buyers.
Different first conversations.
Three adaptable fintech plays. Each connects a buying role, a verifiable reason to research, a useful asset and a handoff rule.
01Business software
+
- Who buys
- Finance operations or product leaders at businesses with the supported workflow.
- A reason to research
- A documented product or geographic expansion provides a reason to ask about the workflow.
- Leave out
- Consumer financial-product prospects and companies outside supported regions or deployment models.
- Bring something useful
- A workflow-fit brief with prerequisites and the implementation responsibilities on each side.
- Start the conversation
- Who owns this workflow, and is evaluating a vendor part of the current project?
- Accept the handoff when
- A buyer confirms the workflow and identifies the implementation owner.
02Platform partnerships
+
- Who buys
- Partnership and product teams at platforms with a compatible use case.
- A reason to research
- A platform publishes an integration ecosystem or partner-development initiative.
- Leave out
- Unverified platform compatibility and commercial arrangements that require approvals not yet obtained.
- Bring something useful
- An integration brief describing data flow, roles, technical dependencies, and the proposed commercial boundary.
- Start the conversation
- Would a short compatibility review help establish whether a partnership conversation makes sense?
- Accept the handoff when
- Both teams identify a concrete use case and owners for commercial and technical review.
03Institutional sales
+
- Who buys
- A business sponsor supported by IT, security, and procurement at a financial institution.
- A reason to research
- A published vendor opportunity or confirmed modernization initiative matches the product.
- Leave out
- Assumed compliance gaps, unsupported savings claims, and institutions outside product scope.
- Bring something useful
- A vendor-evaluation checklist with evidence requirements and responsibility for each review.
- Start the conversation
- What is the correct evaluation route for this vendor category?
- Accept the handoff when
- An authorized sponsor confirms relevance and the required review process.
ReplyLead recommendations. Adapt the message to the actual evidence; these are not tested winning scripts. Download the three-play worksheet.
Related buying route: Vendor acquisition into financial institutions.
04 / KNOW WHAT THE SOURCE PROVES
Useful evidence.
Clear boundaries.
The source should change the account decision. Record its date and the field it actually supports; keep the missing information visible.
| Source or artifact | Use it for | Still needs confirmation |
|---|---|---|
| Product / API documentation | Supported deployment model and documented interfaces | Documentation alone does not prove a buyer's installed version is compatible. |
| Technical owner confirmation | Current systems, responsibility and test access | Do not infer the current stack from a third-party technology tag. |
| NIST CSF | Language for organizing risk-management responsibilities | Not a certification or a diagnosis of the prospect. |
Reference: NIST Cybersecurity Framework. Account-specific sources in this table are evidence to collect, not claims that a prospect has been verified.
FIRST-PARTY MEASUREMENT
2.12%Median unique replies per contacted lead.
81 campaigns with at least 500 contacted leads.
Know what the number measures.
ReplyLead's frozen August 12, 2026 extraction includes automatic replies and mixes client and internal programmes. It is a cross-campaign reference, not an industry target, positive-reply rate or meeting forecast.
For an industry cohort, separate human replies, positive replies, booked meetings, held meetings and sales-accepted opportunities. Keep the contacted-person denominator and maturity window consistent. A result from a different audience is not a substitute for your segment's evidence.
Inspect the benchmark definitions and datasetSource: ReplyLead campaign benchmark, checked 24 September 2026.
BEFORE YOU LAUNCH
The questions that
change the brief.
What does the fintech integration-dependency mapper produce?
A product demo cannot resolve who owns the integration. Map the workflow, data scope, system owners and test environment before proposing a pilot. It exports your entered inputs, the resulting decisions and the next actions as a CSV working brief.
What qualifies a fintech lead for a sales handoff?
Capture the workflow, deployment boundaries, integration owner, buyer, confirmed requirements, review dependencies, and next evaluation step. Keep a partner introduction separate from a direct customer opportunity.
Are the examples measured ReplyLead client results?
The annotated examples are illustrative planning cases. The 2.12% benchmark is separately identified first-party mixed-programme evidence with automatic replies included. No industry conversion rate is inferred from it.
How to use this field guide.
Choose a buying situation, work through the decision lab, and attach a source and date to the facts that drive the result. Confirm unresolved requirements with the appropriate owner before launch. The tool rules are visible in the worked example and produce a planning brief from your inputs; they do not verify accounts or predict campaign outcomes.
ReplyLead runs cold email and LinkedIn. Review the operating process, commercial terms and documented client examples when evaluating a managed program.
Where judgment still matters.
Funding and hiring announcements are context, not proof of purchasing intent. Do not infer transaction volume, fraud exposure, creditworthiness, or an upcoming provider switch. A payment-related job title does not tell you who owns integrations or procurement.
The playbooks address B2B account acquisition. They do not establish contact permission or a legal determination. Apply your organization's contact, suppression and jurisdiction review before outreach.
Sources behind the method.
Checked 24 September 2026. Public references support the stated definitions. Account-specific facts still need a dated record from the buyer or an appropriate primary source. The planning choices and examples are ReplyLead recommendations.
- NIST Cybersecurity Framework: Common risk-management language for vendor discussions; not a product certification.
- ReplyLead benchmark and methodology: the scoped cross-campaign statistic above.
- ReplyLead operating process: cold email and LinkedIn program context.
- Google sender guidelines: Authentication and sender requirements for personal Gmail recipients. Checked 24 September 2026.
- Yahoo sender best practices: Yahoo-specific requirements to review before a campaign; separate from account fit. Checked 24 September 2026.
- RFC 5321: SMTP: Transport acceptance is separate from inbox placement or a human response. Checked 24 September 2026.
- Census NAICS: Classification describes establishments; verify the actual business activity and buying unit. Checked 24 September 2026.
BUILD WITH REPLYLEAD
Bring the market.
Leave with a sharper brief.
Bring your target buyer, delivery boundaries and the working brief. Define the account evidence, message and sales handoff for your industry.
Discuss your fintech program