REPLYLEAD / INDUSTRY FIELD GUIDE
Financial services lead generationReach the institution.
Navigate the review.
Keep B2B vendor acquisition separate from consumer financial-product promotion.
THE BUYING PROBLEM
Financial services is a market.
What is the decision?
This financial-services playbook concerns business-to-business acquisition: reaching organizations that may buy an operational service, professional service, or technology. It is not a consumer investor or borrower prospecting guide. Define the institution type, operating region, buying function, and permitted service scope before discussing an outreach program. A vendor conversation requires different qualification from promoting a financial product.
The costly targeting mistake
Do not infer investable assets, credit need, distress, or individual financial circumstances from a company record. A regulated entity identifier can help resolve identity but does not establish a relationship, budget, or permission. Route regulated messaging and regional requirements to the responsible internal reviewer.
01 / WORK THE PROBLEM
Financial-services vendor-review planner.
Selling services to a financial institution involves a business sponsor and a review route. Map the outstanding documents and owners without confusing a checklist with approval.
Illustrative inputs loaded. Edit them to build your own brief.
Calculations run in your browser. This tool makes no live account lookup. Our tool events record action names, not your field values.
YOUR WORKING BRIEF
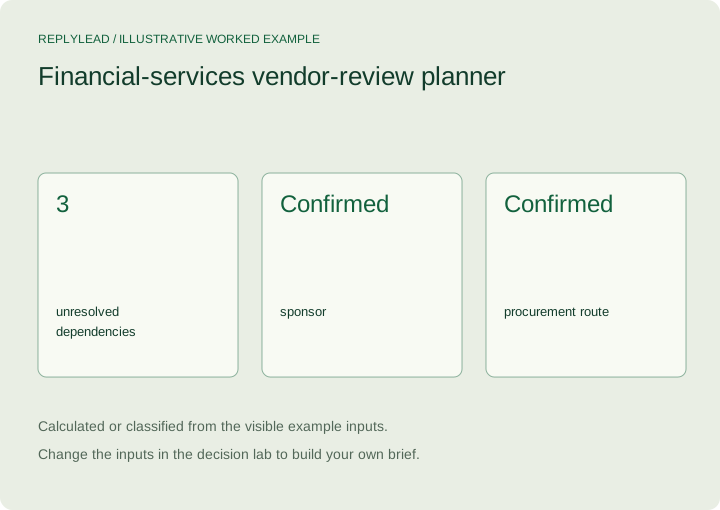
3 review dependencies to resolve
| Requirement | Decision |
|---|---|
| Institution | Illustrative Regional Institution |
| Sponsor | Confirmed |
| Security documents | Requested, missing |
| Data scope | Not defined |
| Procurement route | Confirmed |
| Contract reviewer | Unknown |
Next actions
- Confirm the requested security documents and prepare the missing items.
- Document the data-handling scope and its owner.
- Name the contract-review owner.
- Confirm the contracting legal entity. Prepared documentation does not mean approval or compliance.
02 / FOLLOW THE REASONING
Watch the evidence
change the next step.
ILLUSTRATIVE CASE / NOT A CLIENT RESULT
The brand and the contracting entity differ
In this illustrative vendor sale, a brand-level contact is interested but the legal entity that would contract must still be recorded.
Parallel interest is not completed review
A sponsor is confirmed. Procurement has a route. Security documentation is missing, data-handling scope is undefined and the contract reviewer is not yet named.
Export a dependency list
Send each unresolved item to its owner. Keep commercial interest and review readiness as separate fields; the tool does not decide compliance, approval or suitability.
03 / SELECT THE COMMERCIAL ROUTE
Different buyers.
Different first conversations.
Three adaptable financial services plays. Each connects a buying role, a verifiable reason to research, a useful asset and a handoff rule.
01Operational services
+
- Who buys
- Operations leaders at the institution type and region your service supports.
- A reason to research
- A public branch, platform, or operating-model change creates a relevant workflow question.
- Leave out
- Consumer prospects, unsupported distress assumptions, and institutions outside your authorized delivery scope.
- Bring something useful
- A vendor scope sheet describing responsibilities, dependencies, and review ownership.
- Start the conversation
- Who owns the vendor evaluation for this operational workstream?
- Accept the handoff when
- The institution confirms a relevant vendor category and an evaluation owner.
02Technology vendors
+
- Who buys
- IT, security, operations, and the business sponsor at financial institutions.
- A reason to research
- An institution publishes a technology initiative or a relevant vendor opportunity.
- Leave out
- Claims that a public technology signal proves a control weakness or imminent purchase.
- Bring something useful
- A deployment and review matrix covering systems, data boundaries, and procurement dependencies.
- Start the conversation
- Would a scope and dependency summary help your team decide whether to evaluate this?
- Accept the handoff when
- A sponsor confirms a business use case and the technical or procurement review route.
03Professional partnerships
+
- Who buys
- Business owners or partnership leaders at complementary service firms.
- A reason to research
- A firm describes an expansion or partnership strategy relevant to your expertise.
- Leave out
- Conflicts, unsupported referral arrangements, and consumer-product solicitation disguised as a partnership.
- Bring something useful
- A partnership brief with service boundaries and explicit responsibilities for review and client communication.
- Start the conversation
- Is there an appropriate person to review the partnership scope and its boundaries?
- Accept the handoff when
- The counterpart confirms fit and identifies who can review the arrangement.
ReplyLead recommendations. Adapt the message to the actual evidence; these are not tested winning scripts. Download the three-play worksheet.
Related buying route: Fintech software and integration acquisition.
04 / KNOW WHAT THE SOURCE PROVES
Useful evidence.
Clear boundaries.
The source should change the account decision. Record its date and the field it actually supports; keep the missing information visible.
| Source or artifact | Use it for | Still needs confirmation |
|---|---|---|
| GLEIF reference data | Legal-entity identification where an LEI exists | Does not prove buying intent, regulatory approval or vendor eligibility. |
| Institution vendor process | The institution's current requested documents and submission route | Requirements depend on the institution and the proposed service. |
| Named internal owners | Sponsor, security, data and contracting responsibilities | A completed document is not the same as an approved review. |
Reference: GLEIF introduction to the LEI. Account-specific sources in this table are evidence to collect, not claims that a prospect has been verified.
FIRST-PARTY MEASUREMENT
2.12%Median unique replies per contacted lead.
81 campaigns with at least 500 contacted leads.
Know what the number measures.
ReplyLead's frozen August 12, 2026 extraction includes automatic replies and mixes client and internal programmes. It is a cross-campaign reference, not an industry target, positive-reply rate or meeting forecast.
For an industry cohort, separate human replies, positive replies, booked meetings, held meetings and sales-accepted opportunities. Keep the contacted-person denominator and maturity window consistent. A result from a different audience is not a substitute for your segment's evidence.
Inspect the benchmark definitions and datasetSource: ReplyLead campaign benchmark, checked 24 September 2026.
BEFORE YOU LAUNCH
The questions that
change the brief.
What does the financial-services vendor-review planner produce?
Selling services to a financial institution involves a business sponsor and a review route. Map the outstanding documents and owners without confusing a checklist with approval. It exports your entered inputs, the resulting decisions and the next actions as a CSV working brief.
What qualifies a financial services lead for a sales handoff?
Record the legal entity, vendor category, confirmed business problem, sponsor, reviewer, procurement route, and permitted next step. Do not collect customer financial information through an outbound brief.
Are the examples measured ReplyLead client results?
The annotated examples are illustrative planning cases. The 2.12% benchmark is separately identified first-party mixed-programme evidence with automatic replies included. No industry conversion rate is inferred from it.
How to use this field guide.
Choose a buying situation, work through the decision lab, and attach a source and date to the facts that drive the result. Confirm unresolved requirements with the appropriate owner before launch. The tool rules are visible in the worked example and produce a planning brief from your inputs; they do not verify accounts or predict campaign outcomes.
ReplyLead runs cold email and LinkedIn. Review the operating process, commercial terms and documented client examples when evaluating a managed program.
Where judgment still matters.
Do not infer investable assets, credit need, distress, or individual financial circumstances from a company record. A regulated entity identifier can help resolve identity but does not establish a relationship, budget, or permission. Route regulated messaging and regional requirements to the responsible internal reviewer.
The playbooks address B2B account acquisition. They do not establish contact permission or a legal determination. Apply your organization's contact, suppression and jurisdiction review before outreach.
Sources behind the method.
Checked 24 September 2026. Public references support the stated definitions. Account-specific facts still need a dated record from the buyer or an appropriate primary source. The planning choices and examples are ReplyLead recommendations.
- GLEIF introduction to the LEI: Legal-entity identification; not a credit, suitability, or buyer-intent assessment.
- ReplyLead benchmark and methodology: the scoped cross-campaign statistic above.
- ReplyLead operating process: cold email and LinkedIn program context.
- Google sender guidelines: Authentication and sender requirements for personal Gmail recipients. Checked 24 September 2026.
- Yahoo sender best practices: Yahoo-specific requirements to review before a campaign; separate from account fit. Checked 24 September 2026.
- RFC 5321: SMTP: Transport acceptance is separate from inbox placement or a human response. Checked 24 September 2026.
- NIST Cybersecurity Framework: Reference vocabulary for vendor risk-management responsibilities; not a prospect diagnosis. Checked 24 September 2026.
- Census NAICS: Classification describes establishments; verify the actual business activity and buying unit. Checked 24 September 2026.
BUILD WITH REPLYLEAD
Bring the market.
Leave with a sharper brief.
Bring your target buyer, delivery boundaries and the working brief. Define the account evidence, message and sales handoff for your industry.
Discuss your financial services program